 Gold Daily Insights
Disclaimer: This article is for educational and informational purposes only and does not constitute financial advice. Trading gold and other leveraged products carries a high risk of loss. Always do your own research and never risk money you cannot afford to lose.
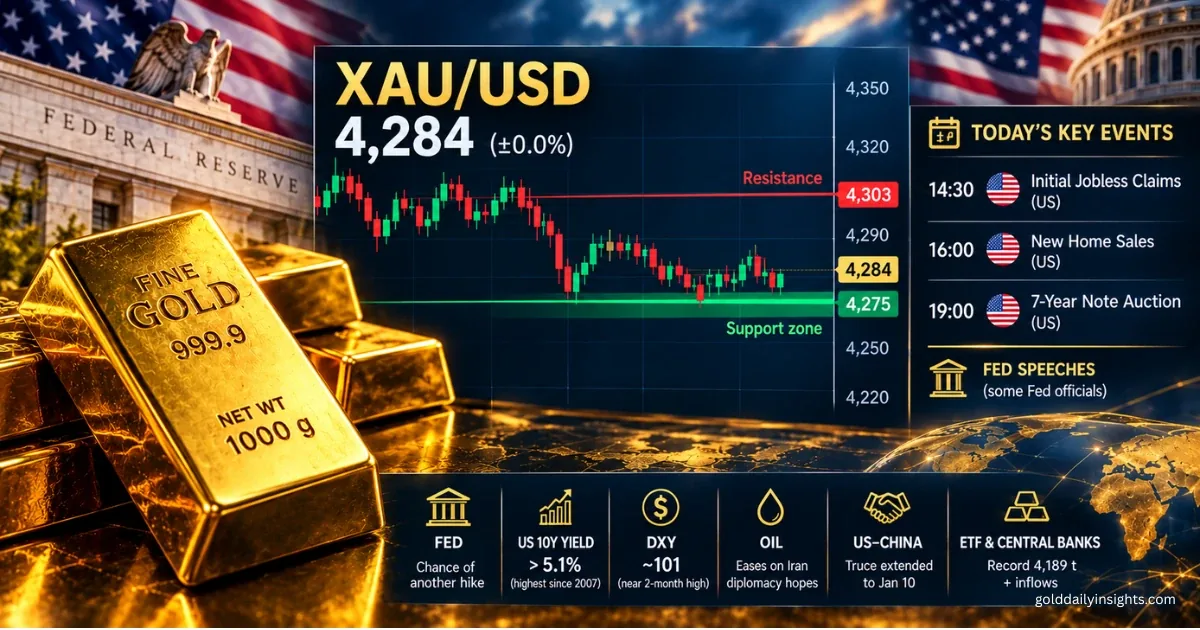
Gold has spent the morning hugging $4,280, and I do not think that is a coincidence. After a sharp sell-off on Wednesday, the market is sitting right on a zone where buyers have stepped in before, and today’s calendar could decide whether they do it again.
Opening
Spot gold is trading around $4,284 as I write, almost flat on the session but well below where it stood earlier in the week. The day range so far runs from roughly $4,274 to $4,303, and yesterday’s close was close to $4,287. On Wednesday gold lost more than 1% and slipped under the $4,300 handle for the first time in several sessions.
The bigger picture is not pretty for the bulls in the short term. Gold is down about 1.3% over the past week and nearly 8% over the past month, although it is still up roughly 14-15% over twelve months. I read that as a market correcting inside a much larger uptrend, not one that has changed direction entirely.
Fundamental Landscape
The story is still the Federal Reserve. Last week’s 25 basis point hike took the federal funds range to 3.75%-4.00%, the first increase since 2023, and the updated projections pointed to at least one more move before year-end. Comments from several Fed officials since then have kept that message alive, and the market now prices a real chance of another hike, with the October meeting firmly on the radar.
That is feeding straight into yields. The US 10-year yield pushed above 5.1% on Wednesday, its highest level since 2007, helped by a very strong flash PMI (the composite jumped to 58.4, the best reading since July 2021) and a weak auction of five-year notes. The dollar index is holding around 101 on the spot measure, close to a two-month high. Gold pays no yield, so when Treasuries offer more than 5% and the dollar is firm, holding bullion becomes more expensive. My reading is that good economic news is currently bad news for gold, because it gives the Fed more reason to stay tight.
The geopolitical side is less clear-cut. Oil has eased a little this morning on signs that Iran remains open to diplomacy, which takes some pressure off inflation fears but also trims part of the safe-haven premium. On top of that, President Trump and President Xi meet in Washington today, and reports suggest the US-China trade truce has been extended to 10 January. A calm summit could soften safe-haven demand further, while any sour headline could do the opposite.
Underneath all this, the structural support has not disappeared. Global gold ETF holdings sit at a record near 4,189 tonnes after another week of inflows, and central banks kept buying in July. I see that as a cushion under the market, even if it does not stop a short-term drop.
Asia & Europe Sessions
The Asian session was a story of a failed bounce. Gold briefly poked back above $4,300 and even touched around $4,303, but sellers pushed it down again almost immediately, and price slid back to the $4,274 area. That rejection at the round number told me a lot about who is in control right now.
By the time London was getting going, gold had steadied and recovered a few dollars, trading in a narrow band between about $4,275 and $4,290. It was quiet, without conviction in either direction, which is typical before a heavy US calendar. I would not read much into that calm.
Technical Analysis
On the higher timeframes the picture is a market that has been making lower highs since the early-September peak. The H4 and H1 charts both show that stair-step lower, and yesterday’s drop took price back into the base of the recent range around $4,270-$4,300. The weekly chart is a useful reminder that this is a pullback inside a large range, well below January’s record near $5,595 but far above where the year began.
On the intraday side, the M30 chart shows gold grinding sideways in a tight box just above $4,275 after the fall. Momentum leans bearish but is not stretched: daily RSI is in the low 40s, not oversold, and the hourly technical readings all lean to the sell side, with the short-term averages sitting above price. The hourly pivot point is close to $4,279, and price is hovering right on top of it, which tells me the market is undecided at this exact spot.
In short, the trend is heavy, but price is sitting on support, so I am respecting both the downside momentum and the chance of a reaction bounce.
Key Levels
- $4,300: the first resistance and the level that rejected price in Asia. A clean move back above it would be the first sign the sellers are tiring.
- $4,345-$4,350: the next recovery zone, where price turned last week.
- $4,400: the major short-term barrier and the top of the recent bounce. A sustained move above would improve the picture considerably.
- $4,500-$4,530: the area I would need to see reclaimed before calling the medium-term structure bullish again.
- $4,275-$4,270: immediate support, containing Wednesday’s low and the hourly pivot area.
- $4,236-$4,230: the September swing low and the most important support below the market.
- $4,200 and $4,160: deeper downside references if $4,230 fails.
My Gold Outlook Today
Main scenario: I lean cautiously bearish while gold stays below $4,300. If yields keep climbing, the dollar holds near 101 and the Fed speakers stay firm, I expect a test of $4,270 and possibly a run at the $4,236 zone.
Alternative scenario: If jobless claims come in weak, yields ease from their highs and the dollar loses some ground, I could see a rebound back through $4,300 towards $4,345-$4,350. That would look like a relief bounce inside a bigger correction, not a full reversal.
Invalidation: For the bearish view, I would want to see gold hold above $4,350 and then push through $4,400. On the downside, a decisive daily close below $4,236 would tell me the correction is deeper than I am assuming and would put $4,200 and $4,160 in play.
What I’m Watching Today
- Fed speakers: John Williams speaks first at 10:10 CEST (09:10 UK), with several other Fed officials scheduled through the day. I am listening for any hint on whether September was a one-off or the start of a sequence.
- US Jobless Claims at 14:30 CEST (13:30 UK): the forecast is 201K against 196K previously. A number well above that would be gold-supportive, while a low print would strengthen the hawkish story.
- New Home Sales at 16:00 CEST (15:00 UK): a secondary release, but housing is one of the sectors most sensitive to high rates, so a big surprise could move yields.
- Trump-Xi headlines and the 7-year note auction (19:00 CEST): summit comments can move the dollar quickly, and another weak auction could push yields, and pressure on gold, higher into the evening.