 Gold Daily Insights
The Shifting Tides of the Global Economy
Sitting here at my desk this morning, sipping an espresso and watching the XAU/USD M30 chart, I am struck by the sheer scale of the macroeconomic shift unfolding before us. Today is the 10th of September 2026, and the geopolitical landscape is undergoing a structural transformation not seen since the collapse of the Bretton Woods system in 1971. It is easy to get lost in the noise of daily candlestick fluctuations, but understanding the long-term capital flows requires stepping back and looking at the foundational architecture of global finance.
The narrative that the United States is facing an imminent collapse is, frankly, an exaggeration. The US dollar remains the dominant force in global finance, accounting for 56.77% of official foreign exchange reserves at the end of 2025. Furthermore, the dollar was on one side of 89.2% of all foreign exchange transactions as of April 2025. However, the reality I am observing is not a sudden death of the dollar, but rather a gradual, deliberate fragmentation of the global monetary order. The world is building the capacity to operate with less reliance on American financial infrastructure.
The $40 Trillion Question
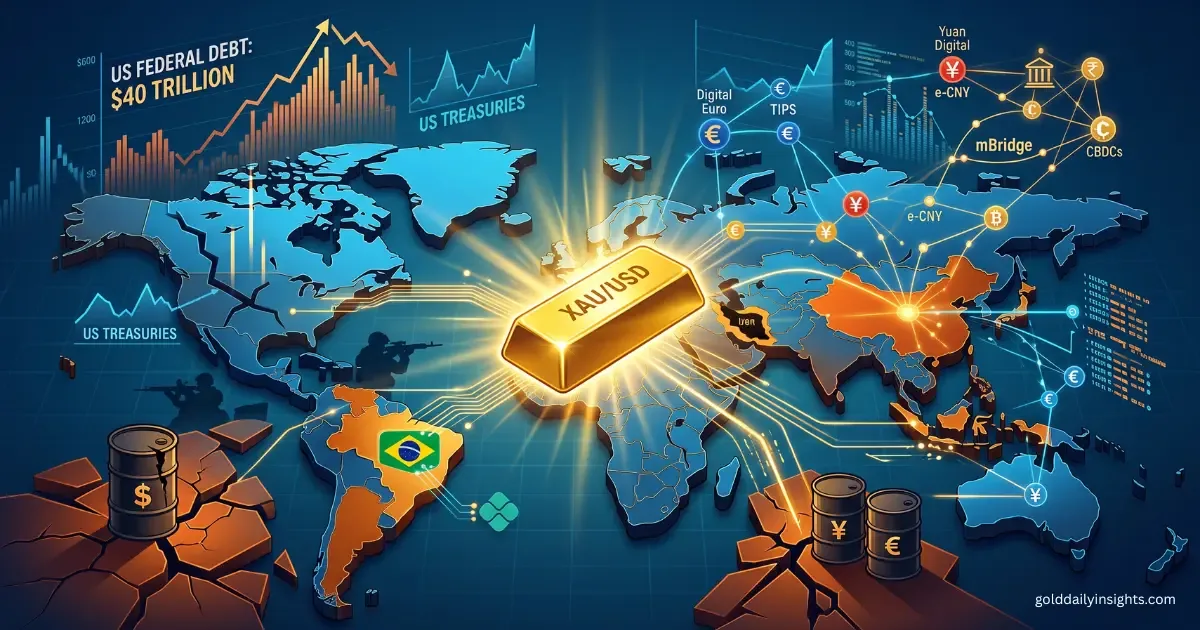
To me, the most glaring catalyst for this shift is the fiscal trajectory of the United States. On the 18th of August 2026, the gross federal debt of the US breached the historic $40 trillion mark for the first time. This figure more than doubled in less than a decade. The Congressional Budget Office (CBO) projects that US federal debt held by the public will surge to 120% of GDP by 2036, up from 101% in 2026.
What I find truly alarming as a market participant is that the cost of servicing this debt now exceeds the total budget of the Pentagon. The US is spending more on past borrowing than on its current military apparatus. With projected deficits continuing to expand despite recent tariff policies, the long-term mathematical reality points toward currency debasement. When a nation’s debt spirals to these levels, maintaining global confidence in its treasury bonds becomes an existential necessity.
Geopolitics, Oil, and the Middle East Quagmire
Compounding this fiscal strain is the unpredictability of US foreign policy and its entanglement in fresh military conflicts. The ongoing war between the US, Israel, and Iran, which began on the 28th of February 2026 with coordinated airstrikes dubbed “Operation Epic Fury”, was initially expected to last only a few weeks. Instead, it has dragged into September, causing significant disruptions to the global energy supply.
This conflict directly impacts the fundamental drivers of XAU/USD. The resulting disruptions in the Strait of Hormuz have choked a significant portion of Gulf oil exports, keeping Brent crude elevated and injecting fresh inflationary pressures into the global economy. Every new conflict strains the US budget further and forces central banks to reconsider their exposure to geopolitical risks.
The Petrodollar Myth and the Multipolar Reality
There is a widespread rumour I often see on trading forums claiming that a 50-year “petrodollar agreement” between the US and Saudi Arabia expired in June 2024, ending the dollar’s monopoly on oil. My reading of historical documents confirms this is a myth; no such formal expiry document ever existed. However, the core truth behind the rumour is highly relevant: Saudi Arabia is actively diversifying.
Riyadh has started accepting payments in Yuan for oil shipments to China and has officially joined Project mBridge. Developed alongside the Bank for International Settlements (BIS), China, Hong Kong, Thailand, and the UAE, mBridge reached its Minimum Viable Product stage in 2024. It is a multi-central bank digital currency (CBDC) platform designed to bypass traditional systems like SWIFT.
The Rise of Sovereign Payment Rails
I am tracking several parallel developments that aim to bypass US financial exclusivity. The Chinese e-CNY is expanding, and the CIPS system moved 1.46 trillion Yuan in March 2026 alone. In Europe, the European Central Bank (ECB) is pushing forward with the Digital Euro. They recently selected 36 service providers for a pilot scheme set to begin in late 2027, eyeing a potential launch in 2029.
Even more fascinating is the cross-border integration of domestic instant payment systems. There are active discussions regarding a pilot project linking Brazil’s Pix system with Europe’s TIPS infrastructure by 2028. Furthermore, the BIS Project Agorá is exploring a tokenised, multi-currency infrastructure. The future I am preparing for is not a world where the Yuan replaces the Dollar, but rather a digital, multi-currency ecosystem where the Dollar, Euro, Yuan, and local currencies operate simultaneously.
Gold: The Ultimate Neutral Reserve
So, where does this leave gold? As sovereign nations construct these isolated financial blocs, they require an asset to settle balances between them—an asset that carries no counterparty risk and cannot be frozen by foreign sanctions. Gold fits this requirement perfectly.
The data clearly illustrates this shift. Central banks purchased 863 tonnes of gold in 2025, significantly above the historical average. The buying accelerated this year, with central banks adding 289 tonnes in the second quarter of 2026 alone. China has been accumulating aggressively, logging its 22nd consecutive month of purchases with a 20.2-tonne addition in August 2026. By early 2026, the total value of global gold reserves surpassed $4 trillion, eclipsing the value of US Treasuries held by central banks. According to the World Gold Council, 74% of reserve managers expect the dollar’s share of global reserves to decline over the next five years, and 45% plan to increase their gold holdings.
My Gold Outlook
My base case remains unequivocally bullish for the long term. In September 2026, we saw the price of gold touch $4,425 an ounce. While short-term intraday price action on my M30 charts will continue to be dictated by Federal Reserve rate expectations and immediate inflation data, the macroeconomic floor beneath gold is rock solid.
I am watching the ongoing fragmentation of the global monetary order carefully. As the US manages its $40 trillion debt pile and digital sovereign currencies gain traction, gold will cement its position not as a challenger to the dollar, but as the essential, neutral insurance policy for the digital multipolar era.